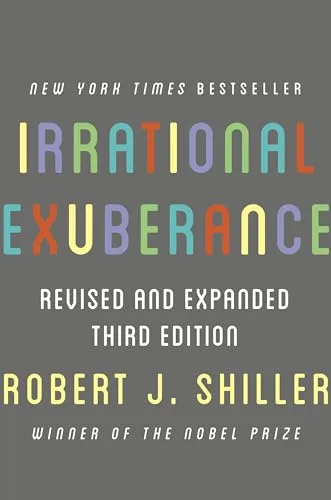
Irrational Exuberance
- Published
- 2000
- Pages
- 392 pages
- Publisher
- Princeton University Press
- Readers
- 2 members have read this
Robert Shiller's study of why asset prices overshoot, first published in March 2000 at the peak of the dot-com bubble and later extended to housing and bonds. Using more than a century of data and his cyclically adjusted P/E, he shows how news, new-era stories and herd behavior push markets past fundamentals. Essential for anyone who has to judge whether a market is expensive.
Shiller argues that the level of the market is set as much by psychology and feedback loops as by fundamentals. Rising prices feed on themselves through what he calls naturally occurring Ponzi processes, in which past gains attract new buyers, and he traces the 1990s boom to factors from the internet to the growth of 401(k) plans and cheap online trading.
The title borrows Alan Greenspan's 1996 warning. Shiller, a Yale economist, co-developed the cyclically adjusted price-earnings ratio (CAPE) and shared the 2013 Nobel Prize with Eugene Fama and Lars Peter Hansen. The timing made his name: the first edition appeared in March 2000, the month the Nasdaq peaked, and the 2005 second edition warned of a housing bubble. The 2015 third edition adds the bond market.
It is a founding text of behavioral finance and the main popular counterweight to the efficient-markets view. Fama's retort is the fair caveat: Shiller has been consistently bearish, so given enough time he will be right about some crash. The book explains bubbles far better than it times them, and CAPE says little about the next year's returns.
Read it if you allocate capital, set return assumptions or need a disciplined way to argue that a market is overpriced.
- Valuation is a long-horizon signal. High cyclically adjusted P/E ratios have historically been followed by weak returns over the next decade, but they say little about next year.
- Bubbles feed on themselves. Rising prices generate stories, media coverage and new buyers, and that feedback, not a single cause, carries prices away from fundamentals.
- Every peak has a new-era story. The internet in 2000 and the supposed safety of housing in 2005 echoed the arguments made at earlier tops in 1901 and 1929.
- Housing and bonds bubble too. Shiller found that inflation-adjusted home prices returned less than 1 percent a year over the long run, which made the 2000s run-up look abnormal, and by 2015 he saw similar risks in long-term bonds.
- Diversify against your own exuberance. His practical advice is broader diversification and policies that help people manage risk, not trying to call the top.
Opening chapters set current valuations against Shiller's long series of US stock prices and earnings and, in the third edition, bond yields and home prices. The book then runs in five parts.
- Structural factors. The precipitating factors behind booms, including the internet and the capitalist explosion after 1989, and the amplification mechanisms, feedback loops in which rising prices bring in more buyers.
- Cultural factors. How the news media spread market stories, and the new-era thinking that has accompanied every major peak from 1901 and the 1920s to the 1990s and the housing boom.
- Psychological factors. The quantitative and moral anchors that tie investors to prices, and the herd behavior and word-of-mouth epidemics through which ideas spread.
- Attempts to rationalize exuberance. A critique of efficient-markets theory and of popular beliefs such as the idea that investors have learned that stocks always win in the long run.
- A call to action. Policy proposals to reduce the damage from bubbles, and advice to individuals to diversify more broadly, across countries and asset classes, rather than chase the market that has risen most.
Reader reviews
No reviews yet. Join to write the first one.