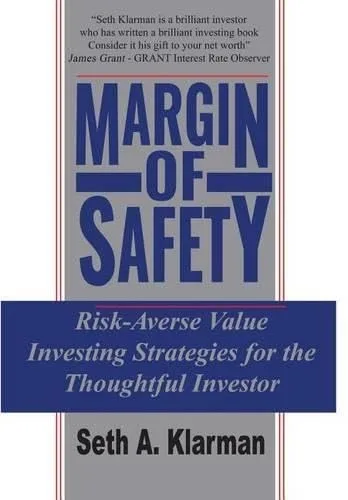
Margin of Safety
Risk-Averse Value Investing Strategies for the Thoughtful Investor
- Published
- 1991
- Pages
- 249 pages
- Publisher
- HarperBusiness
- Readers
- 3 members have read this
Baupost founder Seth Klarman's only book, and the best modern statement of value investing as a discipline of avoiding loss. He shows why Wall Street and institutional money managers work against their clients, how to value a business conservatively, and where bargains hide, from spinoffs to bankrupt debt. Long out of print, it remains one of the most sought-after investing books.
Seth Klarman learned the trade at Mutual Shares, then co-founded the Baupost Group in 1982. He wrote this book in 1991, about a decade into what became one of the most successful records in the hedge fund business, and later edited the sixth edition of Graham and Dodd's Security Analysis.
The book applies Graham's ideas to markets of the late 1980s. Klarman's starting point is that avoiding loss comes before chasing return, and that the margin of safety is the gap between price and a conservative estimate of value. He is skeptical of precise forecasts, prefers adequate valuations to exact ones, and is blunt about the incentives on Wall Street and among institutional managers: short-term performance races, herd behavior and benchmark hugging driven by career risk.
What sets it apart is its practicality, from catalysts and distressed securities to the case for holding cash when nothing is cheap. Some examples are dated, and readers who know The Intelligent Investor will find the core ideas familiar.
The original edition sold only about 5,000 copies. It has never been reissued, and used copies sell for hundreds or thousands of dollars. Anyone who finds one, in a library or elsewhere, should read it, especially analysts and portfolio managers who want a risk-first framework.
- Avoid loss first. A single severe loss can wipe out years of compounding, so the first job is to protect capital, not to hit a return target.
- Risk depends on the price you pay. The same asset can be safe at one price and dangerous at another. The margin of safety is the discount to a conservative value.
- Prefer adequate valuations to precise ones. Forecasts can be precise and still wrong. Use several conservative methods and buy only at a big discount to all of them.
- Look where institutions cannot or will not go. Spinoffs, complex securities, bankruptcies and other neglected niches are cheap because large managers avoid them.
- Cash is a position. When no bargains exist, holding cash is better than lowering standards. The point is to sell when you want to, not when you have to.
The book has three parts that move from what goes wrong for investors to a value philosophy and then to the day-to-day process. The third and longest part, The Value-Investment Process, is broken out here in three steps.
- Where most investors stumble. Klarman separates speculators from investors, explains how Wall Street's short-term, bullish bias works against clients, describes the institutional performance derby in which the client is the loser, and takes apart the myths of 1980s junk bonds.
- A value-investment philosophy. He asks readers to define their goals in terms of avoiding loss, makes the case for a margin of safety, explains why value investing works, and sets out the art of business valuation, including net present value, liquidation value and market comparisons.
- The process: finding opportunity. Chapters on research and on catalysts, market inefficiencies and institutional constraints show where bargains come from.
- The process: specialized niches. He works through two areas Baupost knew well: thrift conversions and financially distressed and bankrupt securities.
- The process: running the portfolio. The closing chapters cover portfolio management and trading, diversification, liquidity and holding cash, and the alternatives open to individual investors, followed by a glossary.
Reader reviews
No reviews yet. Join to write the first one.