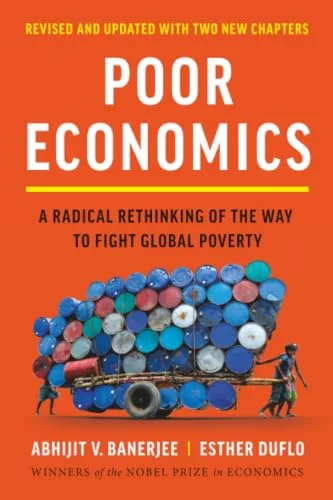
Poor Economics
A Radical Rethinking of the Way to Fight Global Poverty
by Abhijit Banerjee and Esther Duflo
- Published
- 2011
- Pages
- 400 pages
- Publisher
- PublicAffairs
- Readers
- 2 members have read this
Two MIT economists, later Nobel laureates, use randomized field trials to show how the world's poorest households actually decide what to eat, how to borrow, save, insure and school their children. For finance readers it is a ground-level study of credit, savings and risk where markets are thin, and a lesson in testing a theory before betting on it.
The development debate of the 2000s was a shouting match between Jeffrey Sachs, who wanted much more aid, and William Easterly, who thought aid did more harm than good. Abhijit Banerjee and Esther Duflo step around both camps. Their question is narrower and more useful: which specific programs work, for whom, and why? To answer it they lean on randomized controlled trials run across five continents, plus a great deal of listening to poor families.
The authors run MIT's Abdul Latif Jameel Poverty Action Lab, which they co-founded, and in 2019 they shared the Nobel prize in economics with Michael Kremer for that work. The book won the 2011 Financial Times and Goldman Sachs Business Book of the Year award. Nicholas Kristof praised it in the New York Times for moving the argument from whether aid works to which aid works best, and Easterly himself gave it a warm review in the Wall Street Journal.
Critics have pushed back. Madeleine Bunting in the Guardian found the authors naive about power, and the economist Sanjay Reddy faulted it for studying single interventions in isolation from their context and for leaving little room for politics. It also carries little formal theory beyond the idea of poverty traps.
Finance readers will get the most from the middle chapters on microcredit, insurance and saving, which explain why markets for these products are so hard to build for poor customers. The 2025 revised edition adds material from a further decade of research.
- Test before you scale. Randomized trials settle questions that ideology cannot, and many plausible programs turn out to do little. The same discipline applies to any investment thesis.
- Credit is not a cure-all. Microfinance helps households smooth consumption and run small ventures, but it does not lift most borrowers out of poverty or fund businesses that grow.
- Uninsured risk shapes behavior. Without insurance, poor households choose safe, low-return activities and lose assets after shocks. Missing risk markets cost as much as missing capital.
- Saving is a behavioral problem. Poor families could often save more than they do. Commitment devices and safe accounts matter because self-control fails under pressure, as it does for the rich.
- Small frictions have big effects. Tiny costs, defaults and nudges change take-up of vaccines, fertilizer and savings products, which is a reminder that product design often matters more than price.
After an opening case for small, testable questions over grand theories, the book covers the private choices poor families make, then the institutions that shape them.
- Food and health. Most of the very poor are not short of calories in the way aid campaigns assume, and cheap grain rarely helps much. Targeted nutrition for pregnant women and young children pays off. In health, poor families skip cheap preventive measures yet spend on unnecessary treatment, and the authors argue for subsidies and defaults over appeals to reason.
- Schooling and family. The authors weigh whether poor countries lack schools or parents lack reasons to use them, then ask why families have many children and invest unevenly among them.
- Risk and insurance. Poor households face large risks to health, harvests and income with almost no formal insurance. Informal mutual help and microinsurance run into credibility, moral hazard and adverse selection, so the authors favor public subsidies for premiums.
- Credit and saving. Microfinance helps but does not transform lives or fund larger firms, and lenders are exposed to borrower runs. Low saving is explained more by self-control and the lack of safe places to save than by lack of means.
- Entrepreneurs and policy. Most small businesses of the poor are a fallback rather than a calling, and owners would prefer steady jobs. The book closes by arguing that ignorance, ideology and inertia, not just bad politics, explain why policies fail, and that small changes can still move outcomes.
The winners of the Nobel Prize in Economics upend the most common assumptions about how economics works in this gripping and disruptive portrait of how poor people actually live. Why do the poor borrow to save? Why do they miss out on free life-saving immunizations, but pay for unnecessary drugs? In Poor Economics, Abhijit V. Banerjee and Esther Duflo, two award-winning MIT professors, answer these questions based on years of field research from around the world. Called marvelous, rewarding by the Wall Street Journal, the book offers a radical rethinking of the economics of poverty and an intimate view of life on 99 cents a day. Poor Economics shows that creating a world without poverty begins with understanding the daily decisions facing the poor.
Reader reviews
No reviews yet. Join to write the first one.