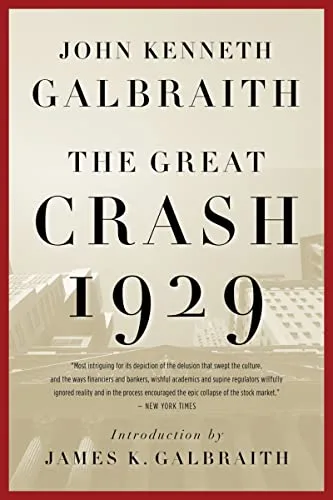
The Great Crash 1929
- Published
- 1955
- Pages
- 224 pages
- Publisher
- Mariner Books
- Readers
- 2 members have read this
Galbraith's short, dry-witted history of the 1929 boom and bust: margin debt, pyramided investment trusts, bankers who promised support and politicians who did nothing. It is still the clearest account of how a speculative mania builds and breaks, and why people keep believing they can get rich without work.
The Harvard economist John Kenneth Galbraith wrote this book in 1954, a quarter century after the crash, and it has not been out of print since. His subject is speculation itself. His argument is that the crash came from mass speculation and the belief that wealth could be had without effort, and that knowing what happened in 1929 is the best protection against a repeat.
Galbraith is a sharp, ironic writer, and the book is short. He is merciless about the people who should have known better, from Charles Mitchell of National City Bank calling the market sound to the Federal Reserve dithering over its discount rate. The closing chapter weighs how far the crash caused the Depression and points to weaknesses in income distribution, corporate and banking structure and economic policy.
The main caveat is depth. Galbraith worked largely from contemporary newspapers and official documents, and later historians, notably monetary economists, put more weight on the Fed's errors after 1929 than on the crash itself. For data and modern scholarship, read it alongside newer histories. As a portrait of mania and the self-deception of the people running the system, it has not been bettered.
Anyone who lived through 2000, 2008 or a recent meme-stock or crypto boom will recognize the pattern. The current Mariner paperback adds a foreword by his son, the economist James K. Galbraith.
- Manias rest on a shared belief. Galbraith's common thread is the conviction that one can get rich without work. When that belief spreads, prices lose touch with any value underneath.
- Leverage on leverage is the accelerant. Margin loans and trusts holding other trusts made gains look brilliant on the way up and wiped out holders on the way down.
- Organized support does not hold. The bankers' pool of October 1929 steadied prices only briefly before the collapse resumed. Promises from authorities cannot stop forced selling for long.
- Reassurance from insiders is a warning sign. Bankers, officials and economists kept saying fundamentals were sound right up to and after the break.
- A crash is dangerous when the system is fragile. The damage of 1929 came from weak banks, overleveraged holding companies and policy mistakes, so look at the structure, not just the market.
The book moves chronologically from the boom of the late 1920s through the aftermath in nine short chapters, the last of them an analysis of causes.
- The setting. Galbraith sketches the optimism of the Coolidge years, the Florida land boom and its collapse in 1926, and the easy-money decision the Federal Reserve made in 1927.
- Something should be done? As brokers' loans soar, officials at the Fed and in Washington debate restraint and do little. Charles Mitchell of National City Bank offers credit to keep the market up.
- In Goldman, Sachs we trust. The investment trust craze peaks with Goldman Sachs Trading Corporation and its offspring Shenandoah and Blue Ridge, whose leverage on leverage magnifies gains and later losses.
- The crash. Through the autumn of 1929 the market breaks: the ticker runs hours late on Black Thursday, the bankers' pool at J.P. Morgan briefly supports prices, and then the late-October collapse arrives.
- Aftermath. Reassurances fail, prices grind toward the 1932 bottom, and reputations fall, including Richard Whitney, later convicted of theft.
- Cause and consequence. Galbraith asks how much the crash caused the Depression and lists the economy's structural weaknesses, from top-heavy incomes to fragile banks and pyramided holding companies.
Arguing that the 1929 stock market crash was precipitated by rampant speculation in the stock market, Galbraith notes that the common denominator of all speculative episodes is the belief of participants that they can become rich without work. It was Galbraith's belief that a good knowledge of what happened in 1929 was the best safeguard against its recurrence.
Atlantic Monthly wrote, "Economic writings are seldom notable for their entertainment value, but this book is. Galbraith's prose has grace and wit, and he distills a good deal of sardonic fun from the whopping errors of the nation's oracles and the wondrous antics of the financial community."
Reader reviews
No reviews yet. Join to write the first one.