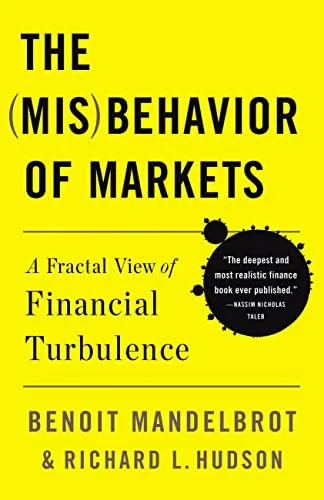
The Misbehavior of Markets
A Fractal View of Financial Turbulence
by Benoit B. Mandelbrot and Richard L. Hudson
- Published
- 2004
- Pages
- 368 pages
- Publisher
- Basic Books
- Readers
- 1 member has read this
The mathematician who invented fractal geometry argues that the bell-curve models at the heart of modern finance badly understate how often prices jump, crash and cluster. Written for general readers with former Wall Street Journal editor Richard Hudson, it is the clearest case for fat tails and wild randomness, and a direct challenge to how most desks still measure risk.
Benoit Mandelbrot spent decades arguing that markets do not move the way finance textbooks say they do. This book, written with journalist Richard L. Hudson, makes that argument for a general audience. Standard tools such as Markowitz portfolio theory, the Capital Asset Pricing Model and Black-Scholes option pricing assume price changes are independent and roughly normally distributed. Mandelbrot shows that real prices have fat tails, long memory and volatility that comes in bursts, so ruinous moves happen far more often than those models predict.
Few people were better placed to make the case. Mandelbrot, a Yale professor and longtime IBM researcher, began studying cotton prices in the early 1960s and found the same jagged patterns at every time scale. Hudson, who spent 25 years at the Journal, keeps the prose plain and moves the equations into endnotes.
The book predates the 2008 crisis but reads like a warning about it. Nassim Taleb, whose The Black Swan leans heavily on Mandelbrot, praised it as the most realistic finance book ever published. Plus magazine found the explanations of scaling and power laws uneven, and Donald MacKenzie in the London Review of Books noted that Mandelbrot's infinite-variance hypothesis remains unproven and his methods are little taught. The practical advice in the last part is general.
Read it to understand why value-at-risk and normal-curve assumptions fail at the worst moments, not for a trading system.
- The bell curve is the wrong default. Price changes have fat tails, so moves that normal-distribution models call near-impossible, such as the Dow's 22.6 percent fall in October 1987, recur.
- Volatility clusters. Turbulent days bunch together, and calm periods are not evidence that risk has gone away.
- Prices jump. Markets often gap rather than move smoothly, which breaks hedging and stop-loss strategies that assume you can trade at every price on the way down.
- Markets have memory. Long-term dependence, the Joseph effect, means trends and bubbles can persist much longer than a random-walk model allows.
- Stress-test beyond the model. Any risk number built on Gaussian assumptions understates the odds of ruin, so size positions and leverage for the tails, not the average day.
The book is organized in three parts: the old way, the new way and the way ahead.
- The old way. Mandelbrot traces modern finance back to Louis Bachelier's 1900 thesis on random price movements, then follows its development through the efficient market hypothesis, Markowitz, Sharpe and Black-Scholes. He closes the section with a case against modern finance's assumptions about investors and price changes, set against the evidence.
- The new way. He introduces roughness and fractal dimension, recounts his study of cotton prices that revealed power laws, scaling and fat tails, and draws on Harold Hurst's research on Nile floods to show long-term dependence in data. Out of this come his Noah effect, sudden violent jumps, and Joseph effect, persistent trends. He then presents multifractal models and compares them with GARCH, the mainstream fix for changing volatility.
- The way ahead. The final part sets out ten heresies of finance, among them that markets are riskier than standard theory assumes, that prices leap rather than glide, that timing matters, that bubbles are inevitable and that forecasting prices is hard. A closing chapter lists the open problems fractal finance has yet to solve.
This international bestseller, which foreshadowed a market crash, explains why it could happen again if we don't act now. Fractal geometry is the mathematics of roughness: how to reduce the outline of a jagged leaf or static in a computer connection to a few simple mathematical properties. With his fractal tools, Mandelbrot has got to the bottom of how financial markets really work. He finds they have a shifting sense of time and wild behaviour that makes them volatile, dangerous - and beautiful. In his models, the complex gyrations of the FTSE 100 and exchange rates can be reduced to straightforward formulae that yield a much more accurate description of the risks involved.
Reader reviews
No reviews yet. Join to write the first one.